Have A Case? Call Us
1 888-536-6671
60 Second Lemon Law Assessment™
60 Second Lemon Law Assessment™
Negative equity from a trade-in does not simply vanish because a car maker agrees to a lemon law buyback. When you roll old debt into a new loan, lender payoff treatment can become complicated, and the result depends on the applicable law, financing documents, offsets, and negotiated terms.
Request a free case review to have Kahn & Associates evaluate your loan documents and possible lemon law claim.
The lemon law negative equity you roll into a new loan is not usually covered during a car maker buyback. While the maker may pay for the faulty car, the buyer must still pay for old debt from a trade-in. Laws in states like Ohio and Florida aim to return you to your first money state. This means the car maker does not have to erase debt you owed before the purchase. If your loan is higher than the car price, you might still owe money after a win. This gap can make a payout tricky and needs a careful review of your deal. Do not think your old debt will go away just because the car is a lemon.
Many drivers are surprised to find that their old car debt follows them. This doubt can lead to a lot of anger during a claim. To find the answer, you must know the link between your loan and car value. The answer begins by showing What does lemon law negative equity mean?
Negative equity is when you owe more on a car loan than the car is worth. Many car buyers call this being “upside down” or “underwater.” This gap between the loan and the car’s trade-in value is common. It often happens because cars lose value fast. If you have a big loan and a small down payment, you may find yourself in this spot.
This case gets more complex when you trade in a car you still owe money on. If the old car is worth less than its loan, the bank rolls that debt into your new car loan. The new loan then covers two things: the price of the new car and the debt from the old one. This makes your total debt much higher than the value of the new car from day one. You can check your lemon law claim value to see how this debt fits into your case.
It is vital to split the cost of your “lemon” from the debt of your old car. The price of a new car usually includes the sticker price, tax, and fees. Negative equity is not part of the price of the new car. Instead, it is a personal debt that you chose to carry over. This split is at the heart of many legal talks during a buyback.
When a car has a flaw that the dealer cannot fix, the Magnuson-Moss Warranty Act and state laws may help you get a refund. These laws aim to hold car makers to blame for the bad goods they sell. But car makers often argue they should only refund the money spent on the lemon. They may claim that your old debt is a personal loan and not a cost of the new car.
Car buyers often feel that the “price paid” should include the full loan amount. They see the rolled-over debt as part of the deal to get the car. But car makers see it in a different way. They believe they are only on the hook for the car they made. They do not want to pay off a loan for a car made by a rival firm years ago. This clash is why negative equity is such a big part of legal cases today.
The goal of a buyback is to put you back in the spot you were in before you bought the bad car. The maker usually offers to pay off the loan and refund your payments. But if your loan includes old debt, the path becomes tricky. To finish a buyback, the maker needs a clear title to the car. This means the whole loan must be paid in full.
If the maker refuses to pay the negative equity part of the loan, you may have to pay that sum yourself to clear the title. This can be a shock for buyers who expect the maker to wipe away all their car debt. Some people find they still owe thousands of dollars even after they give the lemon back. Knowing how lemon law buybacks work helps you get ready for these facts. It allows you to speak with a law firm about how to handle the gap in your loan.
Negative equity is a common issue for car buyers today. It occurs when you owe more on your car loan than the car is really worth. Many people call this being “upside down” on a loan. This often happens when a buyer trades in an old car and rolls the old debt into a new loan.
While this helps you get into a new car, it can cause problems if that car turns out to be a lemon. Dealing with lemon law negative equity requires a clear plan. You will need skilled legal help to work through these complex money issues.
Negative equity starts when you buy a car and the loan balance is higher than the car’s market value. For example, you might owe $20,000 on a car that is only worth $15,000. That $5,000 gap is your negative equity.
This gap often grows when you trade in a car you still owe money on. Dealers may take that old debt and add it to your new loan. This makes your new loan balance much higher from day one. It adds risk if the car has defects.
When your new car is a lemon, the car maker may offer to buy it back. This is called a repurchase. In a standard buyback, the car maker gives back the money you paid for the car. They also pay off your loan so you can walk away.
However, negative equity makes this simple process more complex. The company may argue that they should not have to pay for debt that came from your old car. They only want to pay for the value and costs of the new lemon car itself.
In a lemon law repurchase, the goal is to put you back in the same spot. This is the spot you were in before you bought the lemon. The car maker usually pays for several items. These items often include:
But if you rolled in $5,000 from an old car, the car maker may try to take away that amount. They might say that this debt was not caused by the lemon car. This is a key point in how lemon law buybacks work when debt is involved.
If the car maker does not pay the negative equity, you could be left with a bill. You might have to pay that leftover debt before the company will take the car back. This puts some owners in a tough spot.
They have a car that does not work, but they cannot afford to pay to get rid of it. This is why having a skilled lawyer on your side is so vital. We look at your loan papers to see what the car maker should pay. We base this on state laws and court cases like Gonzalez v. Ford Motor Co.
Every state has its own rules for lemon law claims. For instance, the Florida Motor Vehicle Lemon Law gives clear rights to people with new cars. These rights last for 24 months after you get the car.
In some cases, we can work with the car maker to cover the negative equity as part of a settlement. This often depends on how the loan was set up. It also depends on what the state law says about the price you paid for the car.
We aim to get an agreement that covers as much of your debt as possible. Mileage offsets also play a role in the final check you get. Each state counts this in different ways based on their local laws.
In Ohio, there is no mileage offset in a repurchase. In Florida, the miles at the time of the agreement are used. Michigan looks at the miles before the first repair and anything over 25,000 miles. These rules can change the amount of money you get back.
Our firm has a 97% win rate, which includes cases filed in court. We work hard to ensure you pay nothing out of pocket, win or lose. We seek the best results for your claim and your future.
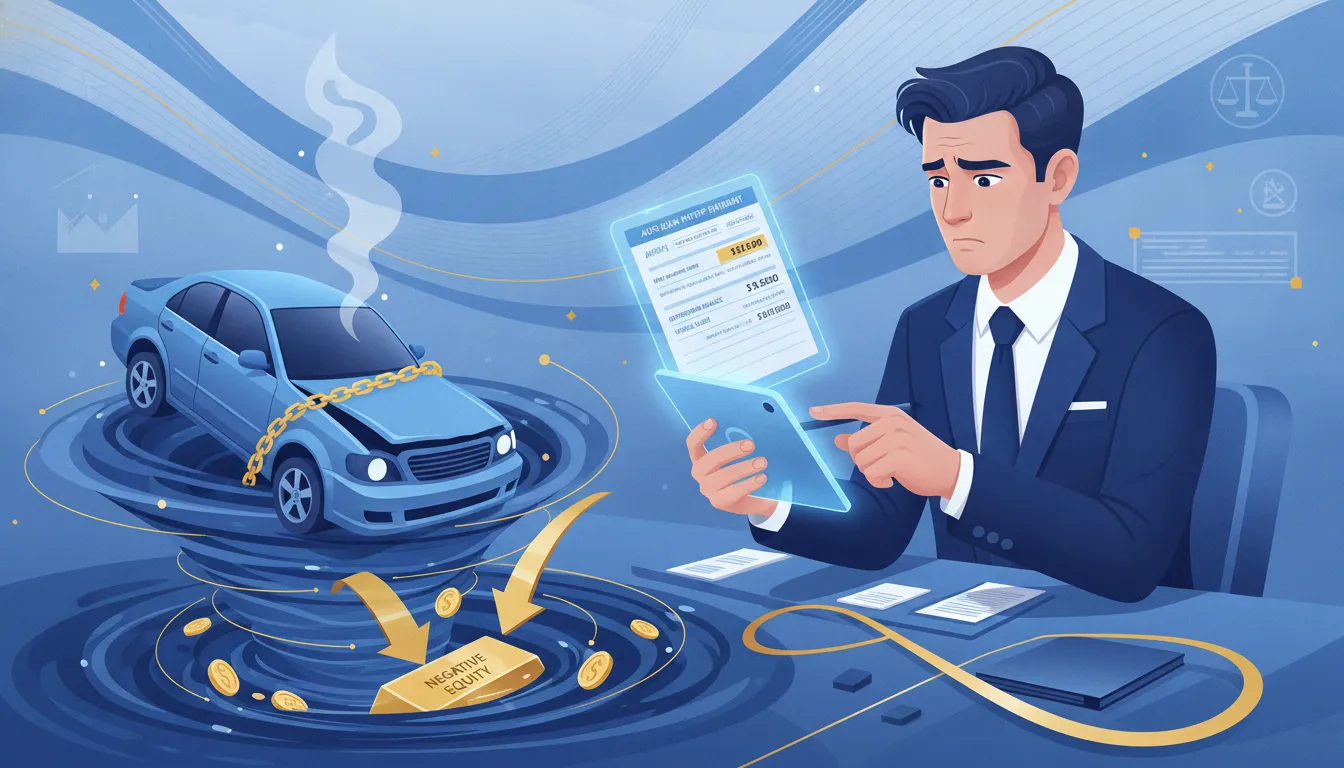
A lemon law buyback calculation is more than just a refund of your car’s price. To calculate your lemon law claim value, legal teams and car makers look at several parts. These things can change the total amount you get back in a settlement or buyback. Each state has its own rules. Many use a similar set of numbers to find the final value.
The base of the math is usually the actual price you paid for the car. This includes any sales tax, title fees, and costs for tags. If you took a loan for the car, the math may also look at the interest you have paid. The goal is to return you to the state you were in before you bought the lemon. But the law varies by state. The exact list of fees that are paid back can differ from one place to the next.
Most states allow the car maker to take a “usage offset” from your refund. This is a charge for the time you could use the car before the defect started. In Florida, the law uses the miles at the time of the settlement for this math (Florida Bar). In Ohio, there is often no mileage offset in a full buyback case. Other states, like Michigan and Pennsylvania, use specific rules based on when the first repair happened. This charge can lower your final check.
If you still owe money on your car loan, the car maker usually pays that off first. The remaining money goes to you. A big challenge comes when you have lemon law negative equity. This happens when you owe more on the loan than the car is worth. It often occurs because you rolled an old car loan into the new one. In many cases, car makers do not have to pay for that old debt. They are only on the hook for the value of the lemon car. You might still owe the bank for that old loan even after the buyback.
You may also get money back for costs tied to the car’s issues. This can include towing fees or the cost of a rental car. Some math looks at repair costs you paid on your own. When you know how lemon law buybacks work, you can better track these costs. Keeping good records of every cent you spend on the lemon is a smart move. This helps your legal team fight for a full and fair settlement.
When you win a lemon law case, the car maker buys the car back. But you seldom get every cent back in your pocket. One big reason is the mileage offset. This is a fee for the time you drove the car before the faults started. Car makers call this a “usage fee.” If you have lemon law negative equity, this fee can make your money spot even harder to handle. The law says you must pay for the good miles you got from the car.
A mileage offset is a charge for the use of your car. The law says it is only fair for you to pay for the miles you drove while the car worked well. Once the car started having defects, that use was no longer worth the full price. Most states use a set path to find this cost. They look at the price you paid and the miles on the dial at a set time. This cost is taken out of your final check.
This fee is not the same as negative equity. Negative equity happens when you owe more on your car loan than the car is worth now. A mileage offset is a legal cut based on state law. If you traded in a car with a high loan, you might already owe the bank extra cash. The mileage offset adds to that gap. You can learn more in our how lemon law buybacks work guide.
Each state has its own way to find the usage fee. Some states are kind to drivers. For example, Ohio does not charge a mileage fee at all in most buyback cases. Other states use the miles you drove before your first repair try. This can save you a lot of cash. But if the state looks at the miles you have now, the fee will be much higher. Knowing these rules helps you calculate your lemon law claim value before you start.
Florida law has exact rules for these cases. In Florida, the miles at the time of your deal are used for the offset. This means if your case takes a long time, the fee might grow. You can find more facts on the Florida Bar consumer tip page about how these rules work. Knowing your state’s rules is the first step to getting a fair deal from the car maker.
The rules vary a lot from one state to the next. In Michigan, the law looks at two sets of miles. They count the miles before the first repair. They also add any miles over 25,000. North Carolina is not the same. They look at the miles on the car at the time of the third repair try. These small things can change your refund by a lot of money. You should have clear lemon law settlement expectations based on your local laws.
| State | Mileage Offset Rule |
|---|---|
| Ohio | No offset for buyback or new car. |
| Florida | Offset based on miles at deal time. |
| Michigan | Miles before first repair plus miles over 25,000. |
| North Carolina | Offset based on miles at the third repair. |
| Pennsylvania | Lesser of 10 cents per mile at first repair or 10% of price. |
Pennsylvania uses a rare “ten percent” rule. They take the lesser of ten cents for each mile at the first repair. Or they take ten percent of what you paid for the car. This cap protects you if you drove many miles before the car broke down. It stops the car maker from taking too much from your check. But if you have lemon law negative equity, you may still need to pay off your old loan with other funds after the case ends.
The sales contract, trade-in disclosures, current payoff statement, payment history, repair orders, warranty, and communications help distinguish the defective vehicle’s cost from rolled-in debt. Together, these records let an attorney evaluate the claim, applicable offsets, and possible lender-payoff terms.
You must gather many papers before you meet with a lawyer. These records help show that your car is a lemon. They also show how much money you lost from lemon law negative equity. Having these files ready will help your case move fast. You need to prove what you paid for the car and what you still owe on your loan. Each piece of paper acts as a tool to build a strong claim against the car maker.
The first things to find are your sales and loan papers. You must have your retail installment contract or lease agreement. These show the price of the car and any trade-in value. If you rolled an old loan into your new one, these records show that debt. You should also keep your buyer’s order and proof that your old loan was paid off. These papers help how lemon law buybacks work by showing your total cost.
If you have negative equity, the maker may not want to pay for it. A court case called Gonzalez v. Ford Motor Co. showed that some judges do not force makers to pay for old debt. This means you might still owe money even after a buyback. You must calculate your lemon law claim value with this in mind. Knowing these numbers early will help you and your lawyer plan your next steps. It is vital to see how much of your loan came from your old car.
You need every repair order and invoice from the dealer. Each time you take the car in for a fix, ask for a copy of the work order. It should show the date you dropped it off and the miles on the car. It must also list the problems you told the dealer about. Even if they could not find a flaw, you should keep the paper. These records prove the car was out of service or had many repair tries. They show a clear path of the car’s failures over time.
The law often counts how many times a car was in the shop. In Florida, Chapter 681 of the Florida Statutes gives rights to those with new cars that stay broken. You must show that the flaw was not fixed after a fair number of tries. Without these repair orders, it is hard to prove your car is a lemon. Each state has its own rules for how many repair tries you need. Keep all invoices in a safe spot so you do not lose them.
Find your owner’s manual and warranty book. These show what the maker promised to fix under their plan. You should also keep a log of every talk you had with the dealer or the maker. Write down the name of the person you spoke with and the date. Save all emails and text logs about the car’s problems. These notes show that you tried to get the maker to fix the car in a fair way. They add a human side to the cold facts of the repair orders.
If you bought extra items like a service contract or GAP insurance, save those papers too. You may be able to get a refund for these as part of your claim. Each piece of paper adds more weight to your case. The more proof you have, the better your chances are of winning. Your lawyer will use these to build a strong claim and push for a fair win. Collecting these files now will save you a lot of time later.
Contact Kahn & Associates for a free review before agreeing to payoff figures or buyback terms.
When you find that your car is a lemon, the path to a buyback involves more than just dealing with the car firm. Since most people finance their cars, the lender plays a key role in how your case ends. Knowing your roles to the bank and how the payoff process works can help you avoid credit traps and money shocks.
The most vital rule to remember during a lemon law case is that your loan deal stays active. You must keep making every monthly payment on time until the buyback is final. Many people think that because the car is a lemon, they should not have to pay for it. However, the bank is a third party that is not to blame for the car’s flaws.
If you stop making payments, the bank can report you to credit bureaus or even take back the car. This can hurt your credit score and make it much harder to get a loan for a new car. Even if your claim is strong, the car maker is not needed to pay your late fees or fix your credit report. Stay current on your loan so that you stay in a good spot during the case.
In a buyback, the car maker wants to take back the car with a clear title. To do this, they must pay off your loan. You will be asked to give a payoff statement from your bank. This paper shows the car maker the exact amount needed to pay off the loan.
The car maker usually sends the payoff money straight to the bank. Once the bank gets the funds, they will release the lien and send the title to the car maker. Under laws like the Ohio Revised Code, a car maker must pay back the full price and costs when they buy back a lemon. After the bank is paid and a cut for your use of the car is taken, any money left is paid to you as a refund.
One of the hardest parts of a buyback occurs when a person has lemon law negative equity. This means you owe more on your loan than the total value of the lemon law refund. This case is common for people who rolled over debt from an old car into their new car loan. Since the maker is only on the hook for the costs of the lemon itself, they often refuse to pay off the old debt.
If your loan balance is higher than the deal amount, you must pay the gap to the bank. This payment is needed to clear the title so the buyback can proceed. It is helpful to calculate your lemon law claim value early to see if you might face this issue. Knowing your out-of-pocket cost helps you make better choices during deal talks.
Before you sign any final papers, you should have a lawyer check the deal. You need to check that the maker is paying the right amount to the bank and that your debt will truly end. A common error is thinking the car maker will handle every detail with your bank on their own.
Your lawyer can help you check that the bank will release the lien fast. They can also ensure that the maker is not taking too large of a cut for the miles you drove. Getting legal help ensures that once you turn over the keys, the loan is gone for good. You can learn more about how lemon law buybacks work to prepare for the final steps of your case.
Finding how negative equity affects a lemon law claim needs a careful review of your car buy contract and loan deal. A lawyer looks at whether the debt rolled into your new loan comes from an old trade-in or from high interest rates. This review is key. Car makers often say they should not have to pay back debts that you had before you bought the bad car.
A legal check helps tell apart your negative equity from your legal pay and the car maker’s offsets. Since the firm helps owners in Ohio, Florida, Michigan, North Carolina, and Pennsylvania, they know the rules for your state. For example, in a Florida lemon law case, the lawyer will account for how mileage offsets work based on the miles at settlement.
In most lemon law buybacks, the car maker must refund the full buy price of the car. This usually includes taxes, fees, and finance costs. But the math gets hard when you have “upside-down” debt. A lawyer helps you know how lemon law buybacks work when negative equity is part of the loan. They work to make sure the car maker does not take more than what is allowed by law.
The check looks at state rules. In Ohio, there is no mileage offset for a buyback. In Michigan, it is based on miles driven before the first repair plus any miles over 25,000. In North Carolina, the math uses miles at the third repair try. Pennsylvania takes the lesser of 10 cents per mile at the first repair or 10 percent of the buy price. A lawyer will check these to make sure the offer is fair.
Beyond the legal rules, a lemon law lawyer can talk out specific terms to handle negative equity. Car makers may not be forced to pay off debt from an old car. Because of this, these items often become points to talk out during a deal. A lawyer can help you calculate your lemon law claim value by looking at your pay versus the loan balance.
They also check if car maker-paid legal fees can be part of the deal. While some state laws, such as Florida’s motor vehicle lemon law, give clear rules for consumer rights, the pay for fees is often agreed during talks. Having a lawyer ensures that these costs do not take from the money you need to pay off your loan. The firm works on a “no win, no fee” basis. You pay nothing unless they win your case.
It is key to know the difference between what the law says and what you owe the bank. If the buyback money does not cover the full loan due to negative equity, you may still owe the rest. A lawyer checks your case to see if more pay can be recovered to help fill that gap. This review helps you decide if a buyback is your best path or if a cash deal would be better for you.
For used cars, a review checks if the car fits the law. The firm handles used cars only when they are still under the car maker’s first warranty. They focus on cases against car makers for warranty issues, not claims against dealers for fraud. This focus helps them check how your loan affects your rights under state and federal law.
Generally, you cannot get a refund for negative equity in a lemon law buyback. Car makers are usually only responsible for the costs tied to the lemon vehicle itself. They are not required to pay for debt rolled in from a previous trade-in. This means if you owed $5,000 on an old car and added it to your new loan. You may still owe that amount to your bank after the car maker repurchases the lemon.
No, gap insurance does not cover negative equity in a lemon law case. Gap insurance is designed to pay the difference between your car’s value and your loan balance if the vehicle is totaled or stolen. Since a lemon law buyback is a legal repurchase and not a total loss from an accident, gap insurance will not apply. You should speak with a lawyer to see if you can get a refund for the cost of the gap insurance policy itself.
Negative equity reduces the amount of cash you receive from a lemon law reimbursement. In a buyback, the manufacturer pays off your loan and refunds your payments. However, they may subtract the amount of negative equity that came from your old car. If your loan payoff is higher than the car’s price because of rolled-in debt. You might have to pay the bank the difference to clear the title and finish the buyback process.
Collateral charges like sales tax and registration fees are usually reimbursable, but those tied specifically to negative equity are not. According to the Florida Statutes, the manufacturer must refund the full purchase price plus certain fees. However, debt from a prior vehicle is not part of the price of the lemon. While you get back the tax you paid on the new car, you do not get back the debt you brought into the deal.
Acting now stops you from being stuck with a car that fails. A car loan that grows each month makes it hard to get a fair deal later. Starting your case today helps you end a bad deal before your car warranty runs out. You can also use our claim value tool to see what your case might be worth. The longer you wait, the harder it can be to show the car maker why they should buy it back. Our team works to make sure you pay no out-of-pocket fees or costs. We deal with the car makers for you so you can move on and get a fair result.
Ready to talk to a lawyer? Request a free case review to schedule a free consultation.
*Disclaimer: The information contained in this Website is provided for informational purposes only, and should not be construed as offering legal advice, or creating an attorney client relationship between the reader and the author. While we aim for accuracy, the law is constantly changing and we make no guarantees regarding the completeness or timeliness of the information. You should not act or refrain from acting on the basis of any content included in this Website without seeking appropriate legal advice about your individual facts and circumstances from an attorney licensed in your state.
To see if you qualify, fill out the form below or call us at 1-888-536-6671 – No Office Visit Needed!
I had a great experience with Kahn & Associates! They made the process of dealing with an extremely frustrating lemon situation painless. They have very quick response times and everyone I dealt with was very friendly and helpful. Would definitely recommend!
Kahn and Associates did an awesome job with our lemon law case! We were getting nowhere with VW Customer Service and decided to hire an attorney who specialized with lemon law cases. We couldn’t be happier with the outcome. We were able to get a full refund on our lemon VW Atlas.
What a great experience! I was on the fence about hiring an attorney for my ongoing automotive issues and continued frustration with the manufacturer. It was a very simple process and I am very grateful Kahn and Associates for helping get me a settlement!
Real Honest attorneys!!! They are the real deal! I went back and forth with them and they explained to me every step and my rights under the law! I give them 5 stars because I won!!! Yes and my check is coming to me much sooner than I thought! I was stuck ! I own a brand new car and the dealer was giving me a hard time !
This page has been written, edited, and reviewed by a team of legal writers following our comprehensive editorial guidelines. This page was approved by Attorney Craig A. Kahn, who has more than 20 years of legal experience in lemon law.
Let’s clear up a big myth about hiring a lawyer for your defective car: that it’s too expensive. The tr...
Hyundai ranks among the most popular vehicle brands in the United States, with the Tucson and Sonata consis...
If you're making monthly payments on a leased vehicle that spends more time at the repair shop than in your...
Stuck with a defective car in Ohio? State Lemon Laws protect you. Get a refund, replacement, or cash settlement. Learn your rights today!
Florida Lemon Laws cover new and used vehicles. If your car’s a lemon, you deserve compensation. Let us help you fight for justice!
Michigan’s Lemon Law protects you from faulty vehicles. Don’t settle for endless repairs—claim your refund or replacement now.
North Carolina Lemon Laws ensure defective vehicles are replaced or refunded. Know your rights and take action today!
Pennsylvania Lemon Law covers new cars with repeated issues. Get the compensation you deserve. Click to learn more!
To see if you qualify, fill out the form below or call us at 1-888-536-6671 – No Office Visit Needed!
The Truth About Attorney’s Fees in Lemon Law Cases Learn more
*Disclaimer: The information contained in this Website is provided for informational purposes only, and should not be construed as offering legal advice, or creating an attorney client relationship between the reader and the author. While we aim for accuracy, the law is constantly changing and we make no guarantees regarding the completeness or timeliness of the information. You should not act or refrain from acting on the basis of any content included in this Website without seeking appropriate legal advice about your individual facts and circumstances from an attorney licensed in your state.

 Message Us
 Call Us